Océalia bought into Cyclair, and with it the parity claim it would need to test
The cooperative now holds equity in the developer whose weeding robots its Cap 2030 plan points toward, which is the reason to want an independent cost test, not the reason to skip one.
Océalia bought into Cyclair, and with it the parity claim it would need to test
Océalia has taken a minority stake in Cyclair, according to industry coverage of the deal, which connects the investment to the cooperative's Cap 2030 plan. Cyclair builds autonomous robots for mechanical weeding. The size, value and terms of the stake are not in the evidence.
The structural consequence is what matters. When a buyer takes equity in a supplier, the capital can fund the supplier's expansion and, on this reading, align its roadmap with the buyer's channel. Whether that is why Océalia invested is not established. What the structure does establish is that the cooperative now holds a financial interest in whether those machines work, whether they are supported, and whether they are priced where members can adopt them. The members would still buy the machines.
A separate fact travels in the same coverage and should not be read into the deal's terms. The parity figure below comes from the company Océalia now part-owns, and no source connects that figure to the stake's pricing. Treat the stake terms and the parity band as two facts, not one.
The robots and the cost case
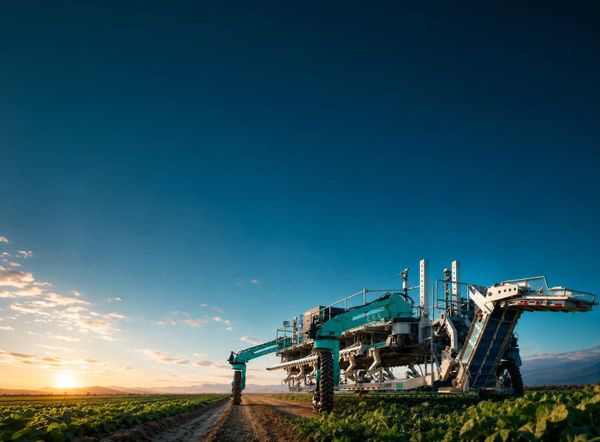
Cyclair makes autonomous robots for precision mechanical weeding in open-field crops under the model names the technology catalogue lists. The ledger records divergent naming across sources, so the model range should be read with that variance rather than as a settled product line. The catalogue lists electric weeding, crop-health sensing and soil sensing as aims, not shipped capability. If those functions ship, the machine would add sensing to its weeding role. A cooperative pricing that layer into a service contract would need a measured yield or input saving to attach to it, and the evidence is silent on whether one exists.
The commercial argument for adoption turns on cost, and here the evidence is thinner than the numbers make it look. Trade coverage reports a per-hectare band, €35-€85 in euro summaries and $40-96 in a dollar aggregator listing, presented as per-hectare cost figures whose parity basis is not established in the evidence. The euro and dollar forms are the same figure republished through the same coverage chain, not two measurements. Neither form is an independently measured trial result, and the company is the source of the band. Real field conditions include variable weed pressure, crop row geometry, soil type and weather windows. If the band survives those conditions, it is the strongest single argument for adoption. If it holds only under favourable conditions, parity is a marketing position, not an operating one.
Capital changes the incentive
If the cooperative's equity de-risks adoption for members, that is the argument for the deal. The same stake also places the cooperative on the supplier's side of the parity claim, and that is the strongest argument against taking the cooperative's own reading of it as the last word. The risk is an incentive gap rather than an inaccurate figure: the party best placed to fund an independent test now holds equity in the company the test would judge. The evidence shows only structural alignment of interest. It does not show any observed change in how the cooperative vets suppliers, and Océalia's verification practices are not in the packet.
Treat the band as a target and a positioning figure until an independent trial or a member-farm cost record puts a number on it that neither party had a hand in producing.
What the structure does change is the deployment risk profile. A grower buying an unproven weeding robot outright carries capex, residual value, service availability and technology-obsolescence risk. A grower accessing the same machine through a cooperative that has equity in the developer carries a different mix, because the cooperative has an incentive to manage the failure mode that an individual grower would carry alone. That is not a subsidy and not a guarantee. It is a shift in who has the incentive to manage the failure mode.
Where the model stops working
Scale and geography are where the argument stops working. Océalia's footprint is Nouvelle-Aquitaine; nothing in the evidence establishes a deployment, distributor or relevance outside that footprint. For a cooperative-equity channel to travel, the receiving region would need a strong cooperative buying channel and labour and herbicide economics tight enough that a per-hectare service cost lands near a chemical pass. The evidence does not establish that both hold anywhere else, and it says nothing about South Africa or any non-European market. On this reading, the cooperative-channel structure is the more plausible part of the model to travel, though the evidence does not establish that it does.
The thing to watch is not another funding announcement. It is a member-farm cost record: the per-hectare figure a member actually pays, broken out by passes, labour, fuel and downtime, on the crops and field geometry the machines are sold into. That record is the one number that could settle the parity question without either party producing it.